M&M’s quarterly profit rose 25% to ₹4,588 crore. Cars did most of the work, rising costs squeezed margins, and the farm business had an off quarter.
Mahindra & Mahindra’s latest results look like a simple success at first. Revenue and profit both rose 25%. Consolidated revenue for the July–September quarter was ₹57,553 crore, against ₹46,106 crore a year ago. Profit was ₹4,588 crore, against ₹3,673 crore.
The numbers underneath tell a more mixed story. One business is racing ahead, one has paused, and rising costs are pressing on almost all of them.
The SUV engine
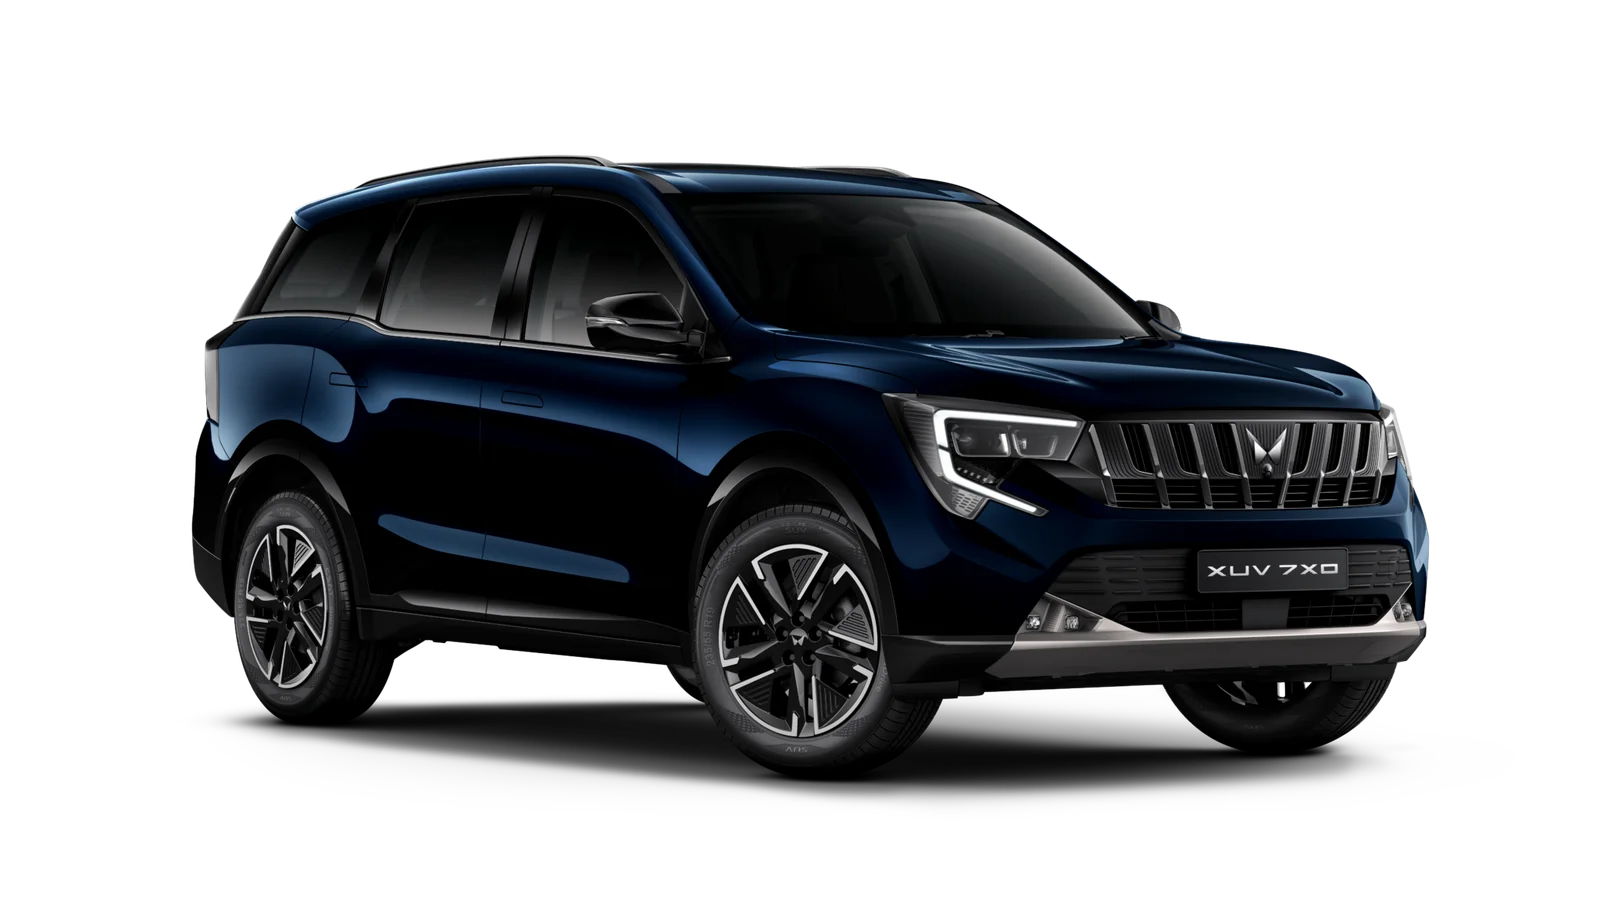
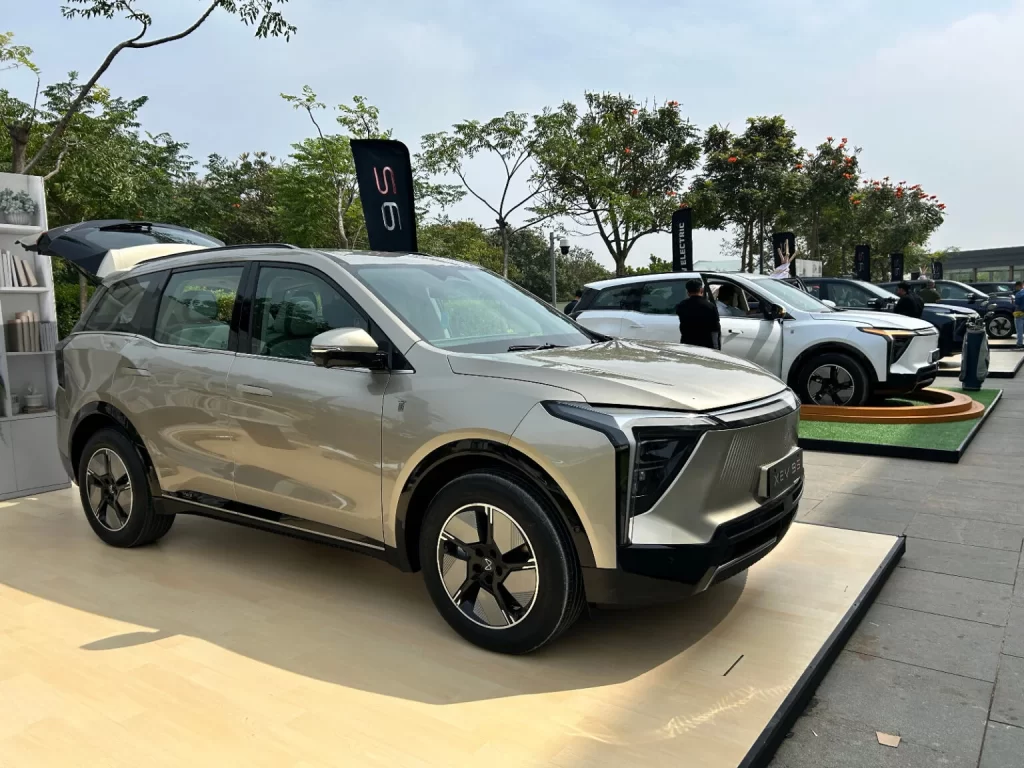
The car business is now the clear centre of the group. M&M sold 3,30,896 vehicles in the quarter, 26% more than last year. Utility vehicles made up about 1,83,000 of them. M&M remains India’s top SUV maker by revenue market share, at 24.3%.
The auto business brought in ₹37,756 crore, up 39%, which is roughly two of every three rupees the group earned. Its profit rose 55% to ₹2,388 crore, more than half of the group’s total.
Revenue grew faster than the number of vehicles sold. That suggests buyers are choosing costlier models and variants, which is good news for any carmaker.
Mr. Rajesh Jejurikar, Executive Director & CEO (Auto and Farm Sector), said, “Auto Business delivered strong performance while Farm business continues to demonstrate strong resilience in Q2F27. SUV volume grew 26% YoY and retained market leadership in revenue market share. EV product range continue to show momentum with maintaining #1 position in revenue market share for the 1st half of the year. Auto consolidated PBIT margin grew to 8.8%, 110 bps up QoQ and Farm consolidated PBIT margin grew 20 bps QoQ despite significant hike in commodity prices.”
Electric bet is gaining ground
Electric vehicles have moved from a side project to a real part of the business. M&M’s electric SUVs hold 30.1% of the eSUV market by revenue. The electric vehicle arm, MEAL, sold 22,864 battery-electric vehicles this quarter, against 12,404 a year ago. That is an increase of about 84%.
Smaller vehicles are growing too. M&M holds 36.2% of the electric three-wheeler market. The last-mile mobility unit, LMM, sold 53,103 vehicles, up about 36%. In light commercial vehicles under 3.5 tonnes, where pickups like the Bolero dominate, M&M holds more than half the market at 52.3%.
Electric growth has a cost, though. The standalone auto business earned a margin of 7.7%. Excluding electric SUVs, the margin would have been 9.1%. That gap shows the EV push is still costly, even as sales rise quickly.
Pause on the farm
Tractors, long M&M’s most reliable business, had a quieter quarter. Sales fell 6% to 1,16,027 units. Farm revenue fell 6% to ₹9,572 crore and profit fell 9% to ₹1,053 crore. The farm margin dropped by three percentage points to 16.8%.
The company blames timing rather than weak demand. Tractor buying in India often peaks around the festive season. This year that season fell differently across quarters, pushing some purchases out of this period. Even in a weak quarter, M&M still sold more than four of every ten tractors in India, with a market share of 41.5%.
Cost squeeze
The clearest warning in the results is in the standalone accounts. Revenue there rose 26% to ₹44,282 crore. Operating profit (EBITDA) rose just 4%, to ₹6,718 crore.
In simple terms, every ₹100 of sales now leaves about ₹15 of operating profit, down from about ₹18 a year ago. Executives point to sharply higher commodity prices and global uncertainty. Steel, aluminium and other materials cost more, and not all of that increase has been passed on to buyers.
There is some relief. The auto margin improved by 0.8 percentage points from the previous quarter, so the squeeze may be easing.
The Group CFO Mr. Amarjyoti Barua said, “Q2 F27 reflects the strength of our diversified portfolio. Our businesses are demonstrating strong operational stewardship and resilience despite significant commodity and geopolitical headwinds. The robust balance sheet and cash generation also provides us the flexibility to invest in future opportunities and deliver sustainable value.”
Beyond vehicles and tractors, M&M’s services businesses grew revenue 18% to ₹11,821 crore, with M&M’s share of their profit also up 18% at ₹1,147 crore.
- Mahindra Finance grew its loan book (AUM) by 15%, and M&M’s share of its profit rose 61%. Bad loans (GS3) stood at 3.42%.
- Tech Mahindra improved its operating (EBIT) margin to 14.8%, up 2.6 percentage points, and M&M’s share of its profit rose 33%.
- Mahindra Lifespaces recorded housing pre-sales of ₹1,100 crore, up 41%.
- Mahindra Holidays reached 5,762 rooms, with occupancy at 76%.
- Mahindra Logistics grew revenue 24% to ₹2,095 crore and returned to profit.
M&M calls its smaller, fast-growing businesses “Growth Gems.” Their combined profit tripled.
The bigger picture
M&M’s spread of businesses showed its value this quarter. When tractors slowed, cars more than made up for it. When costs rose, finance and technology helped hold the total together. The group’s return on equity stood at 21% (annualised, year to date).
The Group CEO and Managing Director Dr. Anish Shah said, “Our Q2 F27 Consolidated PAT growth of 25% reflects the resilience of our group and underlines the disciplined execution across businesses. Auto continued to grow on the back of strong consumer demand, while Farm experienced a marginal decline on account of the festive season shift. Mahindra Finance maintained its growth trajectory, TechM displayed acceleration in its transformation journey, and our Growth Gems continued their momentum. Despite the uneven macroeconomic environment, the group remains focused on laying the foundation for consistent profitable growth.”


